Related articles
Read more
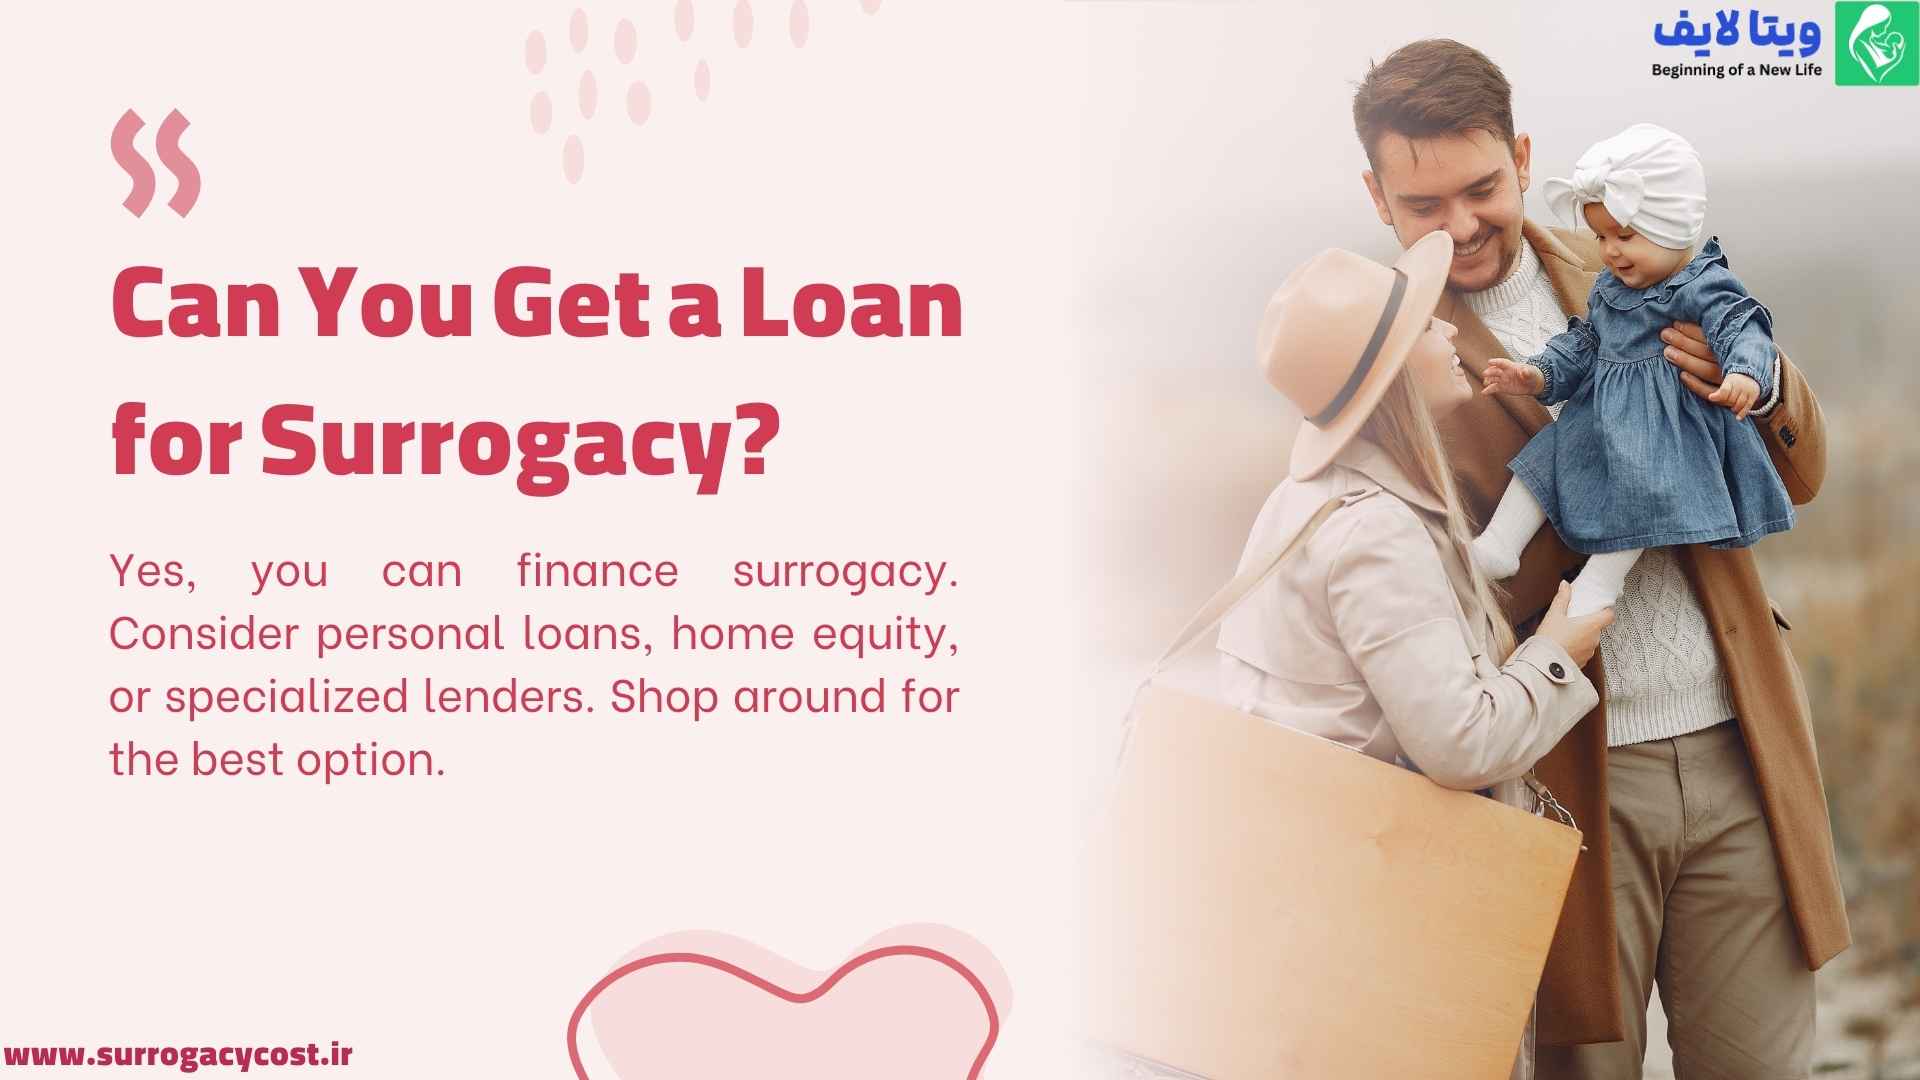
The good news is that surrogacy financing can involve more than one funding source. Personal loans, fertility-specific lenders, employer benefits, grants, savings, and payment plans may all help cover different parts of the journey.
The most effective starting point is to understand the full cost, calculate how much you need to finance, and compare the total cost of borrowing before committing to a loan. A financing plan should make parenthood more manageable without putting your long-term financial security at unnecessary risk.

| Financing Option | Main Benefit | Main Risk or Limitation |
|---|---|---|
| Fertility-specific loan | Designed for fertility-related expenses | Eligibility, interest rates, and covered expenses vary |
| Personal loan | Flexible funding with predictable repayments on fixed-rate loans | Interest rates may be high |
| Home equity loan or HELOC | May offer a lower rate than some unsecured loans | Your home is collateral |
| Employer fertility benefits | May reduce eligible out-of-pocket expenses | Surrogacy and third-party costs may be excluded |
| Grants and scholarships | Funding that generally does not need to be repaid | Competitive and subject to eligibility rules |
| Agency payment plans | Spreads payments across treatment milestones | May not reduce the total cost |
| Savings and family support | Can reduce the amount borrowed | May use money needed for emergencies |
| Crowdfunding | Can mobilize support from friends and community | Funds are uncertain and platform fees may apply |
| Retirement-plan borrowing | May provide access to funds you have accumulated | Can affect retirement security and create tax consequences |
Before choosing a financing option, you need a realistic estimate of the total cost of your journey.
A full-service gestational surrogacy program in the United States can cost approximately $100,000–$200,000 or more. The final amount depends on the provider, the services included, the medical circumstances, and whether additional treatment is needed.
Common expense categories include:
| Cost Category | What It May Include |
|---|---|
| Agency fees | Matching, coordination, screening, and case management |
| Surrogate compensation | Base compensation and agreed benefits or allowances |
| IVF and medical treatment | IVF procedures, embryo transfers, medications, testing, and monitoring |
| Legal expenses | Surrogacy agreements and legal work related to parentage |
| Insurance | Review of available coverage and eligible pregnancy-related expenses |
| Additional services | Egg donation, embryo storage, travel, accommodation, and translation |
| Contingency expenses | Additional treatment, schedule changes, or unexpected costs |
These are cost categories, not a universal price list. Some providers include several items in a package, while others bill them separately.
A low starting price may not represent the total amount you will eventually pay. For example, a quoted agency fee might exclude surrogate compensation, medical costs, insurance, or legal expenses.
Before applying for financing, request an itemized estimate that shows what is included, what is excluded, and which expenses could increase during the journey.
There is no single financing method that works for everyone. Some intended parents use savings and employer benefits, while others combine a loan with grants, family support, or a payment plan.
A useful strategy is to identify money that does not need to be repaid first, then determine whether borrowing is necessary to cover the remaining amount.
Fertility financing companies specialize in loans for reproductive treatment and family building. Some work with fertility clinics, agencies, or financing marketplaces to help intended parents explore available lending options.
Depending on the provider and the loan agreement, eligible expenses may include:
However, coverage differs between lenders. Some may exclude surrogate compensation, international treatment, or payments to providers outside their approved network.
Examples of organizations and services to research include:
These are starting points for research, not endorsements or guarantees of eligibility. Confirm that the lender currently offers a suitable product for your circumstances.
Questions to ask before applying:
Prequalification may help you compare potential offers, but the final rate and loan amount can differ after the lender reviews your application.
A personal loan from a bank, credit union, or online lender may be an option if you need a lump sum to cover surrogacy expenses.
Most unsecured personal loans do not require collateral. Lenders typically consider your credit history, income, existing debts, and ability to make repayments.
Advantages
Disadvantages
Compare several offers rather than accepting the first approval. Review the APR, origination fees, repayment period, late-payment terms, and total amount repayable.
A personal loan may work well for a defined funding gap, but borrowing the maximum amount available can leave less room in your budget for unexpected expenses or future childcare costs.
Homeowners with sufficient equity may consider borrowing against their property.
A home equity loan typically provides a lump sum with scheduled repayments. A home equity line of credit (HELOC) allows you to borrow as needed up to an approved limit and may have a variable interest rate.
These products may offer lower rates than some unsecured loans, but that is not guaranteed.
The major consideration is risk: your home serves as collateral. If you cannot repay the loan, you could face foreclosure. A variable-rate HELOC can also become more expensive if interest rates rise.
Before choosing this route, consider whether your household could manage repayments during parental leave, a change in income, or an unexpected medical expense.
Credit cards and personal lines of credit can provide short-term access to funds, but they should be used cautiously.
Some credit cards offer a promotional 0% interest period. This may help with a specific expense if you can repay the balance before the promotional period ends.
However, promotional rates are temporary, credit limits may be insufficient, and interest can rise sharply once the offer expires.
Before using a credit card for surrogacy, calculate how much you can repay each month and what happens if you cannot clear the balance before interest begins.
High-interest credit card debt is generally a risky way to finance a long and unpredictable process.
Some employer-sponsored retirement plans allow participants to borrow against their vested balance. Others may permit certain withdrawals, subject to plan rules and tax requirements.
Although accessing retirement funds may appear convenient, it can affect your long-term financial security.
Potential concerns include:
Rules depend on the specific plan and your circumstances. Review the plan documents and speak with a qualified financial or tax professional before using retirement savings to fund surrogacy.
Employer benefits are worth checking before taking out a loan. Some employers provide financial support for IVF, fertility medications, egg donation, or other family-building services.
Some plans include benefits for third-party reproduction or surrogacy, but coverage varies considerably.
Ask your HR department for the official plan documents and look for terms such as:
Ask whether the benefit is an annual allowance or a lifetime maximum, which expenses qualify, how reimbursement works, and whether overseas treatment is eligible.
Do not assume that IVF coverage automatically includes surrogate compensation, agency fees, legal expenses, travel, or all pregnancy-related medical costs.
Organizations such as Carrot, Maven, Progyny, and WIN Fertility provide family-building or fertility-related benefits in some employer plans. Availability and coverage depend on the specific employer arrangement.
Grants can reduce the amount you need to borrow because they generally do not require repayment. However, they are often competitive and may have strict eligibility requirements.
Some programs prioritize applicants based on infertility diagnosis, income, medical circumstances, location, or the type of treatment being pursued.
Organizations to research include:
Check each organization’s current application status, deadlines, eligibility requirements, award amount, and permitted use of funds. Some grants support IVF but may not cover agency fees or surrogate compensation.
Apply to several suitable programs when possible, and start early. Grant applications may require medical records, financial information, supporting documents, and time for review.
Treat grants as potential additional funding, not money you can rely on until an award is confirmed.
Crowdfunding allows intended parents to raise money through contributions from friends, family, colleagues, and a wider community.
It may help cover part of the journey, especially when the campaign reaches people who already know and support the family. However, the amount raised is unpredictable, and crowdfunding may not cover a large share of the total cost.
Before launching a campaign:
Crowdfunding can supplement a broader financing plan, but it is risky to rely on it as the only source of funding.
Some intended parents receive a gift or loan from relatives or close friends. If this is an option, agree on the terms before accepting the money.
For a loan, put the amount, repayment schedule, interest if applicable, and expectations in writing. For a gift, clarify whether repayment is expected.
A written agreement can help protect relationships and prevent misunderstandings later.
The advertised interest rate does not tell you the entire cost of borrowing. The annual percentage rate (APR), fees, repayment period, and monthly payment all matter.
| Loan Feature | Why It Matters |
|---|---|
| APR | Helps compare the annual cost of borrowing, including certain fees |
| Interest type | A fixed rate offers more predictable payments; a variable rate may change |
| Origination fee | May reduce the amount you receive or increase the cost |
| Repayment term | Longer terms can lower monthly payments but increase total interest |
| Monthly payment | Must fit your budget alongside existing household expenses |
| Early repayment terms | Check whether there is a penalty for paying the loan off early |
| Eligible expenses | Confirm the lender can fund the costs you need to cover |
Suppose you borrow $30,000 with a fixed 12% APR and repay it over five years. Under a standard monthly amortization schedule, the payment would be approximately $667 per month, and total repayments would be about $40,000 before additional fees.
This is an illustration, not a current loan quote. Actual rates and terms depend on the lender and your financial circumstances.
Before signing, compare the monthly payment and the total amount repayable. A loan with a lower monthly payment is not necessarily cheaper if it runs for a much longer period.
A strong financing plan starts with the full cost of the journey, not the maximum loan you can obtain.
Ask each agency or clinic for a written breakdown of fees and expenses. Make sure the estimate identifies which services are included and which are billed separately.
Ask how the cost could change if screening must be repeated, a surrogate match does not proceed, an embryo transfer fails, or additional treatment is needed.
Check your savings, employer benefits, eligible insurance coverage, and any other family-building benefits before borrowing.
These resources may reduce the amount you need to finance. Confirm coverage in writing rather than relying on a general description of a benefit.
Identify grants for which you qualify and prepare the required documents. You can often pursue applications while comparing loan offers, but do not assume a grant will be awarded.
If a grant is approved, you may be able to reduce the amount you need to borrow, depending on its rules and timing.
Compare APR, fees, repayment terms, monthly payments, early repayment rules, and eligible expenses. Consider consulting a financial adviser if you are weighing a large loan against home equity or retirement savings.
Surrogacy can involve additional treatment, travel changes, or unexpected costs. Set aside an amount for contingencies based on your itemized budget and the risks specific to your journey. A contingency reserve should be realistic and separate from money needed for everyday household expenses.
Loan payments may continue after your child arrives. Include expected childcare, parental leave, insurance, housing, and other family expenses in your budget. Ask yourself whether the repayments will remain manageable if your income changes or additional treatment is required.
Tax treatment varies by jurisdiction and by expense. Do not assume that surrogacy costs, grants, gifts, or crowdfunding contributions are automatically tax-deductible or tax-free. Consult a qualified tax professional about your specific situation and obtain independent legal advice where necessary.
Your financing plan depends partly on the payment structure of the program you choose. Before signing an agreement, ask:
An agency that explains its fee structure clearly makes it easier to estimate how much funding you need and when you will need it.
For intended parents comparing ways to finance surrogacy, VitaLife offers two surrogacy packages in Iran that may be worth considering before taking on a substantial loan.
$18,000 — Standard Surrogacy Package
This package may suit intended parents who want to keep their initial expenses lower. However, additional treatment, if needed, may incur extra costs depending on the terms of the agreement.
$28,000 — Guaranteed Surrogacy Package
Before choosing this option, review the written agreement carefully. It should clearly explain what the guarantee covers, the eligibility requirements, any exclusions, and the circumstances under which coverage may end. Unlimited treatment attempts do not guarantee a live birth in every case.
Potentially. The financial advantage depends on the complete cost of each program, not just the advertised price.
For illustration, the difference between a $150,000 program and an $18,000 package is $132,000 in quoted starting prices. This is not a guarantee of savings or a like-for-like comparison. You would need to compare included medical services, surrogate-related expenses, legal work, travel, accommodation, documentation, and possible additional costs.
Before making a decision, international intended parents should also confirm eligibility, treatment arrangements, parentage procedures, and the requirements for birth registration and travel documentation in their specific circumstances.
Request a written breakdown of the $18,000 and $28,000 packages and compare it with your other quotes before deciding whether financing is necessary.
Surrogacy financing is about more than finding a lender. It means understanding the total cost, comparing funding options, checking available benefits and grants, and making sure future repayments remain manageable.
Start with an itemized quote. Review the resources you already have. Compare loan offers using APR and total repayment costs, and ask detailed questions about additional treatment and payment terms before signing an agreement.
Most importantly, borrow only after you understand the financial commitment and the alternatives available to you. A thoughtful plan can help you pursue parenthood while protecting your family’s long-term financial stability.